What if investing in property depended less on having hours to spare and more on having a clear plan? Property investment when you are too busy can be approached through a well-structured strategy, with the work organised around your goals and the time you can commit. A properly structured investment is estimated to take roughly 20 to 30 hours of an investor’s time per year.
It’s understandable to feel that research, finance decisions and rental responsibilities make property investing difficult to fit around work and family. The answer isn’t to rush into a purchase or assume every investment runs itself. It’s to understand what needs your attention and where practical support or a different investment structure may help.
This article explains how a clear strategy can guide your decisions, how property funds differ from direct ownership, and what practical steps can make investing more manageable when time is limited. You’ll also learn what to consider about ongoing responsibilities, so you can assess which approach best fits your circumstances.
Key Takeaways
- Set investment criteria around your goals, finances and capacity before considering a property, so decisions follow a plan rather than competing for spare time.
- Understand how research, finance and acquisition decisions connect, and where professional guidance can help bring structure to the process.
- Consider how tenancy responsibilities and day-to-day rental tasks affect the time and attention direct property ownership requires.
- Weigh direct property ownership against property funds by considering your preferred level of involvement, along with each option’s risks, fees and withdrawal rules.
A property investment strategy and step-by-step guidance
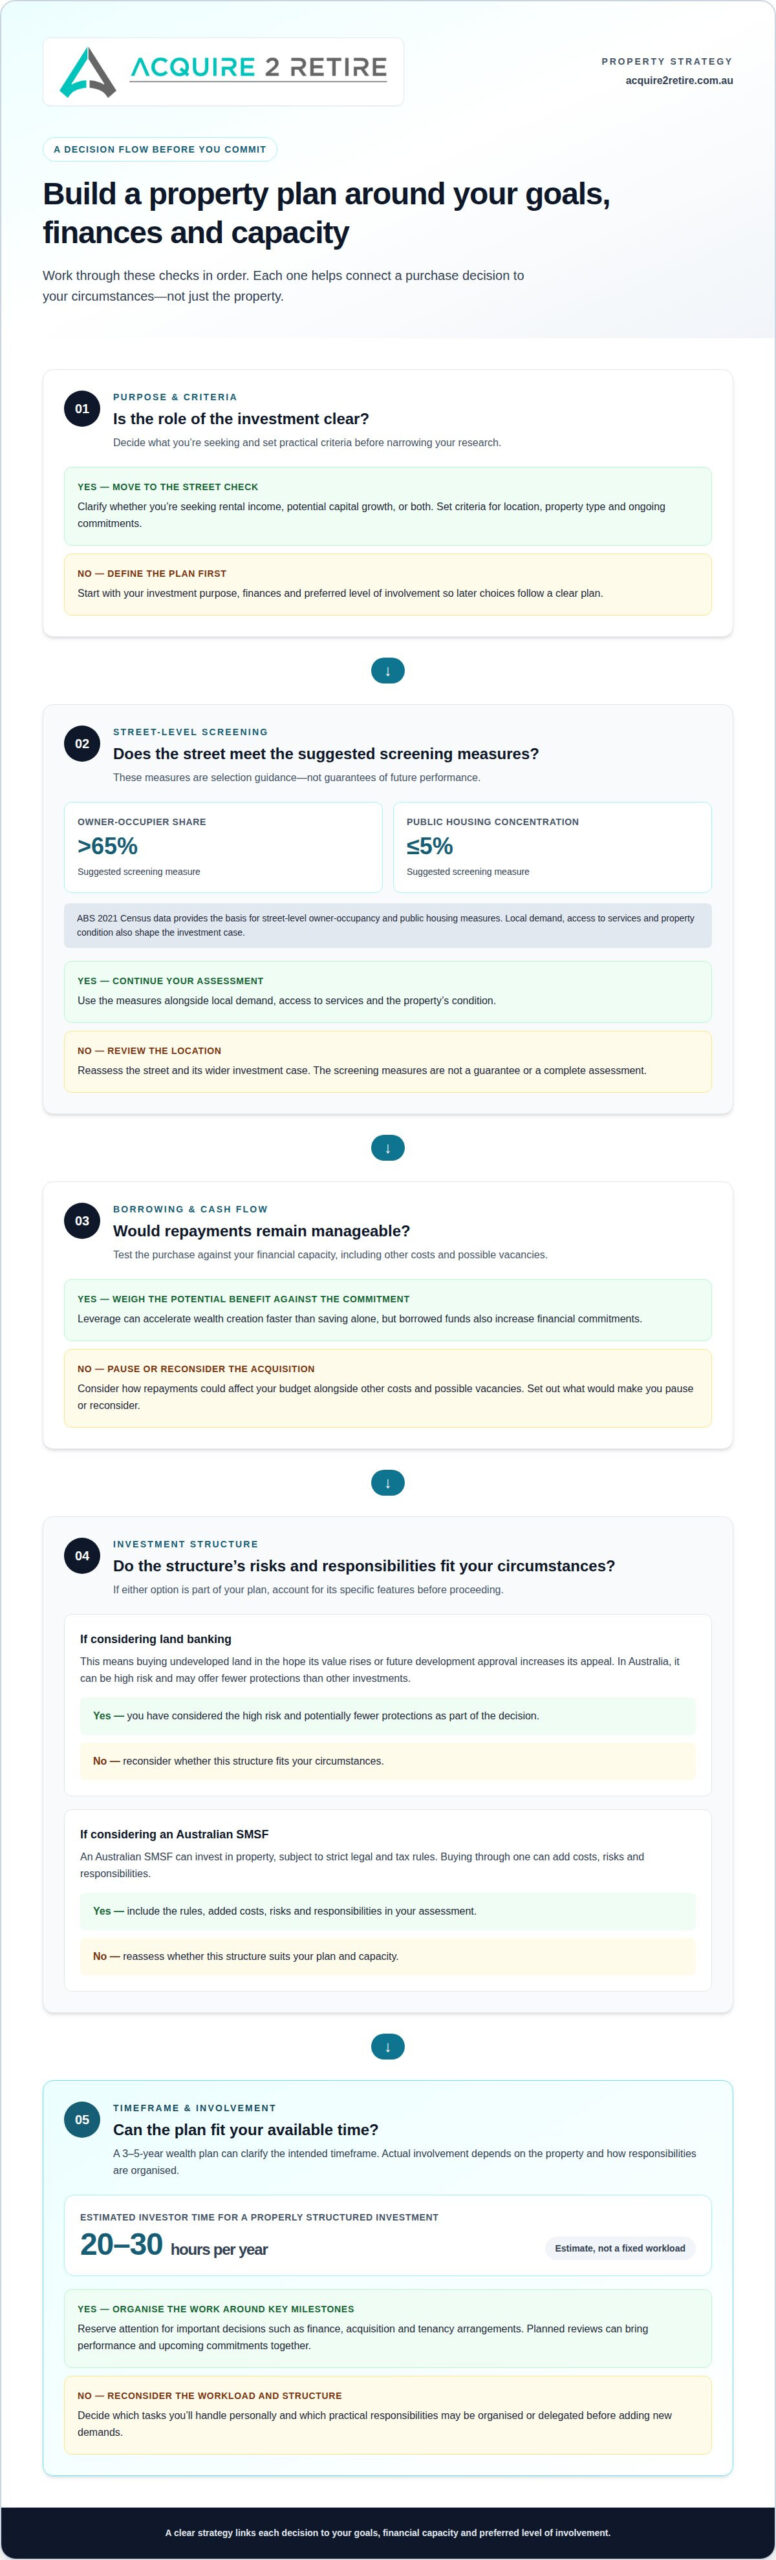
A clear strategy starts with your investment purpose, finances and preferred level of involvement. For a first purchase in 2026, decide what role the property should play in your wider plans. Consider whether you’re seeking rental income, potential capital growth, or both. Then set practical criteria for location, property type and ongoing commitments. These decisions help narrow research and keep each later choice connected to your goals.
Next, assess the street as well as the property. One suggested screening approach looks for owner-occupier share above 65% and public housing concentration no more than 5%. These are selection measures, not guarantees of future performance. ABS 2021 Census data provides the basis for street-level owner-occupancy and public housing measures. Local demand, access to services and the property’s condition also shape its investment case. Professional guidance can help organise these initial decisions around your circumstances.
Then test the purchase against your financial capacity. Consider how borrowing affects cash flow, and whether repayments remain manageable alongside other costs and possible vacancies. Leverage can accelerate wealth creation faster than saving alone, but borrowed funds also increase financial commitments. A sound strategy weighs the potential benefit against the pressure repayments could place on your budget. It also sets out what would make you pause or reconsider an acquisition.
Finally, compare investment structures before committing. Land banking means buying undeveloped land, hoping its value rises or future development approval increases its appeal. In Australia, land banking can be high risk and may offer fewer protections than other investments. An Australian SMSF can invest in property, subject to strict legal and tax rules, and buying through one can add costs, risks and responsibilities. A strategy should account for these features rather than treating every property option as interchangeable. A 3-5-year wealth plan can clarify the intended timeframe, while keeping decisions grounded in your own goals and capacity.
Building wealth through property investing with limited time
Limited time is often a question of priorities and structure, not capacity. A busy professional may struggle to fit property research around work, family and existing commitments. A defined process can reduce repeated decisions by setting criteria in advance. It can also reserve your attention for important milestones, such as finance decisions, acquisition and tenancy arrangements. The goal isn’t to remove every task, but to make each one purposeful.
A properly structured property investment is estimated to take roughly 20 to 30 hours of an investor’s time per year. That estimate gives a useful sense of scale, although actual involvement depends on the property and how responsibilities are organised. Spreading work across planned reviews can make it easier to manage than reacting to each decision as it arises. For example, an investor might set aside time to review portfolio performance and upcoming commitments together.
Waiting also has a potential opportunity cost. A delay of 2 to 4 years means spending that time outside the property market, rather than building experience and exposure through an investment. That doesn’t make an early purchase automatically suitable. It means comparing the cost of waiting with the financial and practical demands of acting now. Income, borrowing capacity, savings and tolerance for risk all affect that assessment.
Property, when structured correctly, can outperform income growth, but outcomes depend on the investment and its performance. An estimate suggests that 20 to 30 hours a year could contribute to $100,000 to $200,000 in wealth through capital growth, equity and time in the market. This is not a promised result; it illustrates the potential relationship between time invested and long-term wealth building.
For a time-poor investor, the useful next step is to connect available time with a realistic investment plan. Property investment planning and strategy can help organise goals, decisions and responsibilities into a coherent approach, before a purchase adds new demands to an already full schedule.
How much time does it take to manage a rental property in Australia?
There isn’t one fixed time commitment for every Australian rental property. The workload changes with tenant requests, repairs, vacancies and the property’s condition. A quiet period may need little attention, while a leaking tap or urgent repair can require prompt coordination. Owners who manage a property themselves also need to keep communication and records organised. The practical question is which tasks to handle personally and which to delegate.
Day-to-day responsibilities can include collecting rent, responding to tenant questions and arranging repairs. A property manager may handle these tasks on the landlord’s behalf. They may also market a rental, arrange inspections, prepare tenancy agreements and process the rental bond. Each task requires follow-up, from organising access for a tradesperson to keeping the tenant informed. When several issues arise together, coordinating a response can take more attention.
There’s also work beyond immediate tenant requests. A property manager may help a landlord meet legal responsibilities and keep up with changes. Regular inspections can identify items that need replacing or updating. A manager may also monitor property value, advise on possible rent increases and report relevant local changes. These activities can inform owners’ decisions, but still require communication and considered follow-through.
Delegation changes the owner’s role; it doesn’t make ownership entirely hands-off. For example, a landlord may still need to decide whether to approve a repair, consider a proposed rent change or respond to a significant property update. Clear communication channels and agreed responsibilities can make those decisions easier to manage. Before investing, consider how much involvement you can accommodate alongside work and other commitments. Then consider which tasks suit your experience and which may be better handled by a property manager. This gives a more realistic picture of the time involved than focusing only on routine rent collection.
Landlords may need to arrange repairs, decide whether to approve them, and use regular inspections to identify items that need replacing or updating. They also need to meet legal responsibilities and keep up with changes. A property manager may help with these tasks.
Is it better to invest in residential property, commercial property, or a property fund when short on time?
There isn’t one best fit for every time-poor investor. The key difference is how much direct involvement an investment requires. With residential or commercial property, you own an asset directly. You may earn rent or benefit from an increase in its value, but you’re also responsible for ongoing costs, vacancies and loan repayments. A property fund offers a different structure, pooling investors’ money under professional management.
Direct ownership gives you a specific property and its associated decisions. For a residential property, those decisions may include responding to vacancies, maintenance needs and tenancy matters. Commercial property also involves direct ownership, so investment performance remains connected to the asset and its rental arrangements. In either case, consider how much attention you can give the property, including when circumstances change.
A property fund may suit someone who prefers property exposure without directly owning a specific building. A professional investment manager oversees pooled money and the fund’s property assets. Funds may provide income and returns if those assets increase in value. However, professional management doesn’t remove investment risk or make every fund equally suitable.
Before investing in a fund, understand its fees, risks and withdrawal rules. These affect potential returns and how readily you can access your money. With direct ownership, weigh rent and possible value growth against costs, vacancies and repayments. Neither route is automatically more convenient; the right fit depends on your preferred level of involvement, financial position and investment goals.
Compare the structures by asking what you’ll own, who makes day-to-day decisions and how you can access funds. Then consider whether direct acquisition or a professionally managed fund better matches your available time. Plan your property investment approach with these trade-offs in view, including the finance and acquisition decisions involved in direct ownership.
Acquire2Retire
Acquire2Retire helps Australian investors bring strategy, acquisition and finance decisions into a considered property investment plan. If limited time makes it difficult to connect research, purchasing and rental responsibilities, its support can help organise those decisions around your goals and circumstances.
Planning & Strategy can shape the investment direction, while Acquisition and Finance support the purchase process. Tenancy coordination can also help organise this part of the investment journey. Together, these offerings provide a practical next step for people weighing direct property ownership against other investment structures, or preparing to move from research towards a purchase.
Contact Acquire2Retire to discuss how a structured approach could fit your property investment plans.
Make your next step a considered one
Property investment when you’re too busy can still begin with one useful decision: what do you want your investments to make possible over time? Defining that purpose gives future choices a reference point, whether your priorities are flexibility, income or building assets for later. It also helps you decide what level of involvement fits your life now, rather than an idealised future schedule.
Before moving ahead, note your priorities, current commitments and main concerns about investing. These can shape a focused conversation about a direction that may fit your circumstances. Starting with those questions doesn’t commit you to a purchase. It gives the decision-making process a clearer foundation and helps keep the next steps connected to what matters to you.
If you’re ready to talk through your options, discuss your next step with Acquire2Retire. A thoughtful beginning can make a complex decision feel more manageable, and help you move forward at a pace that suits you.
Frequently Asked Questions
Too busy to build wealth?
Yes, limited time doesn’t automatically prevent you from building wealth through property. Property investment when you are too busy starts with deciding what you want your investment to achieve, then matching the approach to your finances and available attention. For example, someone unable to respond to tenant issues may prefer an investment structure with less direct involvement. A defined decision process can also help you make progress without repeatedly restarting your research.
What are the best low-maintenance property investment options in Australia for busy investors?
A property fund may suit investors seeking professionally managed property exposure without owning and overseeing a specific building themselves. Direct residential or commercial ownership involves decisions connected to that asset, including tenancy and property matters. If tenant communication would be difficult to fit around work, for example, that may weigh against direct ownership. Consider your preferred level of involvement and investment structure before choosing.
What are the steps to buying an investment property in Australia remotely?
Remote buying can make property investment when you are too busy more practical, provided decisions and local information are coordinated before purchase:
- Set your investment goals and property criteria.
- Review your finance position and borrowing approach.
- Research suitable properties and arrange detailed remote inspections.
- Assess the property, location and tenancy considerations before proceeding with acquisition.
Keep written records of findings, questions and decisions, so you can assess the opportunity without relying on a brief viewing or incomplete information.
What insurance, maintenance, and compliance tasks must Australian landlords handle?
Landlords may need to arrange repairs, decide whether to approve them, and use regular inspections to identify items that need replacing or updating. They also need to meet legal responsibilities and keep up with changes. A property manager may help with these tasks.