Property investing doesn’t have to begin with months of scattered research. A more focused way to learn how to invest in property without researching for months is to assess a clear set of options against your financial position, income goals and plans for building equity. Professional guidance can bring property choices, offer documents and finance considerations into one decision-making process, so attention stays on the factors that matter rather than endless market browsing. The aim isn’t to skip due diligence, but to make it relevant and easier to act on.
It’s understandable to want thorough answers before committing to a major investment, but more information doesn’t always make the decision clearer. This article explains how structured property investment options, careful review of offer documents, financial advice and long-term planning can support a considered path. You’ll see how these elements connect, what they can clarify about potential income and equity growth, and where professional property investment strategy can help turn complexity into a manageable plan.
Key Takeaways
- Focus your property search on a small set of investment options that align with your goals, rather than trying to assess every market and property type.
- Professional review of offer documents can help clarify key terms, risks and the financial advice needed before you commit.
- Consider income, borrowing capacity and future equity together when shaping a long-term investment plan.
- Compare a property’s rental potential and location with the factors that may influence capital growth, without treating either outcome as certain.
Access to property sectors and diversification
A focused comparison helps narrow Australian real estate choices to those that suit your goals, finances and appetite for risk. Diversification can mean spreading exposure across property types, locations or investment structures rather than relying on one purchase. For investors considering how to invest in property without researching for months, professional guidance can help keep comparisons relevant and manageable.
Direct Property, REITs and ETFs
Direct property means owning an investment property, while REITs and property ETFs provide exposure through listed securities. Consider how each may fit your portfolio, including potential income and capital growth, property value and interest-rate exposure. This comparison can clarify whether direct ownership, listed investments or a mix better suits your financial position and desired level of involvement.
Tax deductions and capital gains tax rules depend on the investment and ownership circumstances. Identify questions for a qualified tax adviser, including how rental income, eligible expenses and a later sale may affect your position.
Property Investment Platforms
Australian property investment platforms are online services that present property-related investment opportunities and information through a digital interface. Structures and terms vary, so compare what asset or investment you acquire, how income or returns are handled, and what the offer documents say about access to funds. Understanding these differences helps prevent convenience from obscuring investment risks.
Platforms may offer another route to property exposure, but they don’t replace assessing diversification, liquidity and fit with your broader investments. Review the terms and underlying opportunities to decide whether they complement your other assets.
Professional Quick Property Market Assessment
A professional market assessment brings selected Australian property data together against your goals and financial position. Historical property value trends, rental vacancy rates, comparable sales and weekly auction clearance rates can help frame a purchase decision. RP Data and Australian Property Monitors provide historical price trend data; SQM Research and Australian Property Monitors provide rental vacancy rate data.
Current Australian investment mortgage rates vary by lender and loan terms; lending decisions also consider your finances and the property. Finance advice can compare available structures and explain how interest rates affect repayments, without treating one rate as universal.
A targeted assessment can use comparable sales from realestate.com.au, Domain and realestateView.com.au, alongside location checks for transport, schools and shops. This gives investors seeking how to invest in property without researching for months a way to focus on relevant evidence instead of an unfiltered market search.
Professional review of offer documents and financial advice
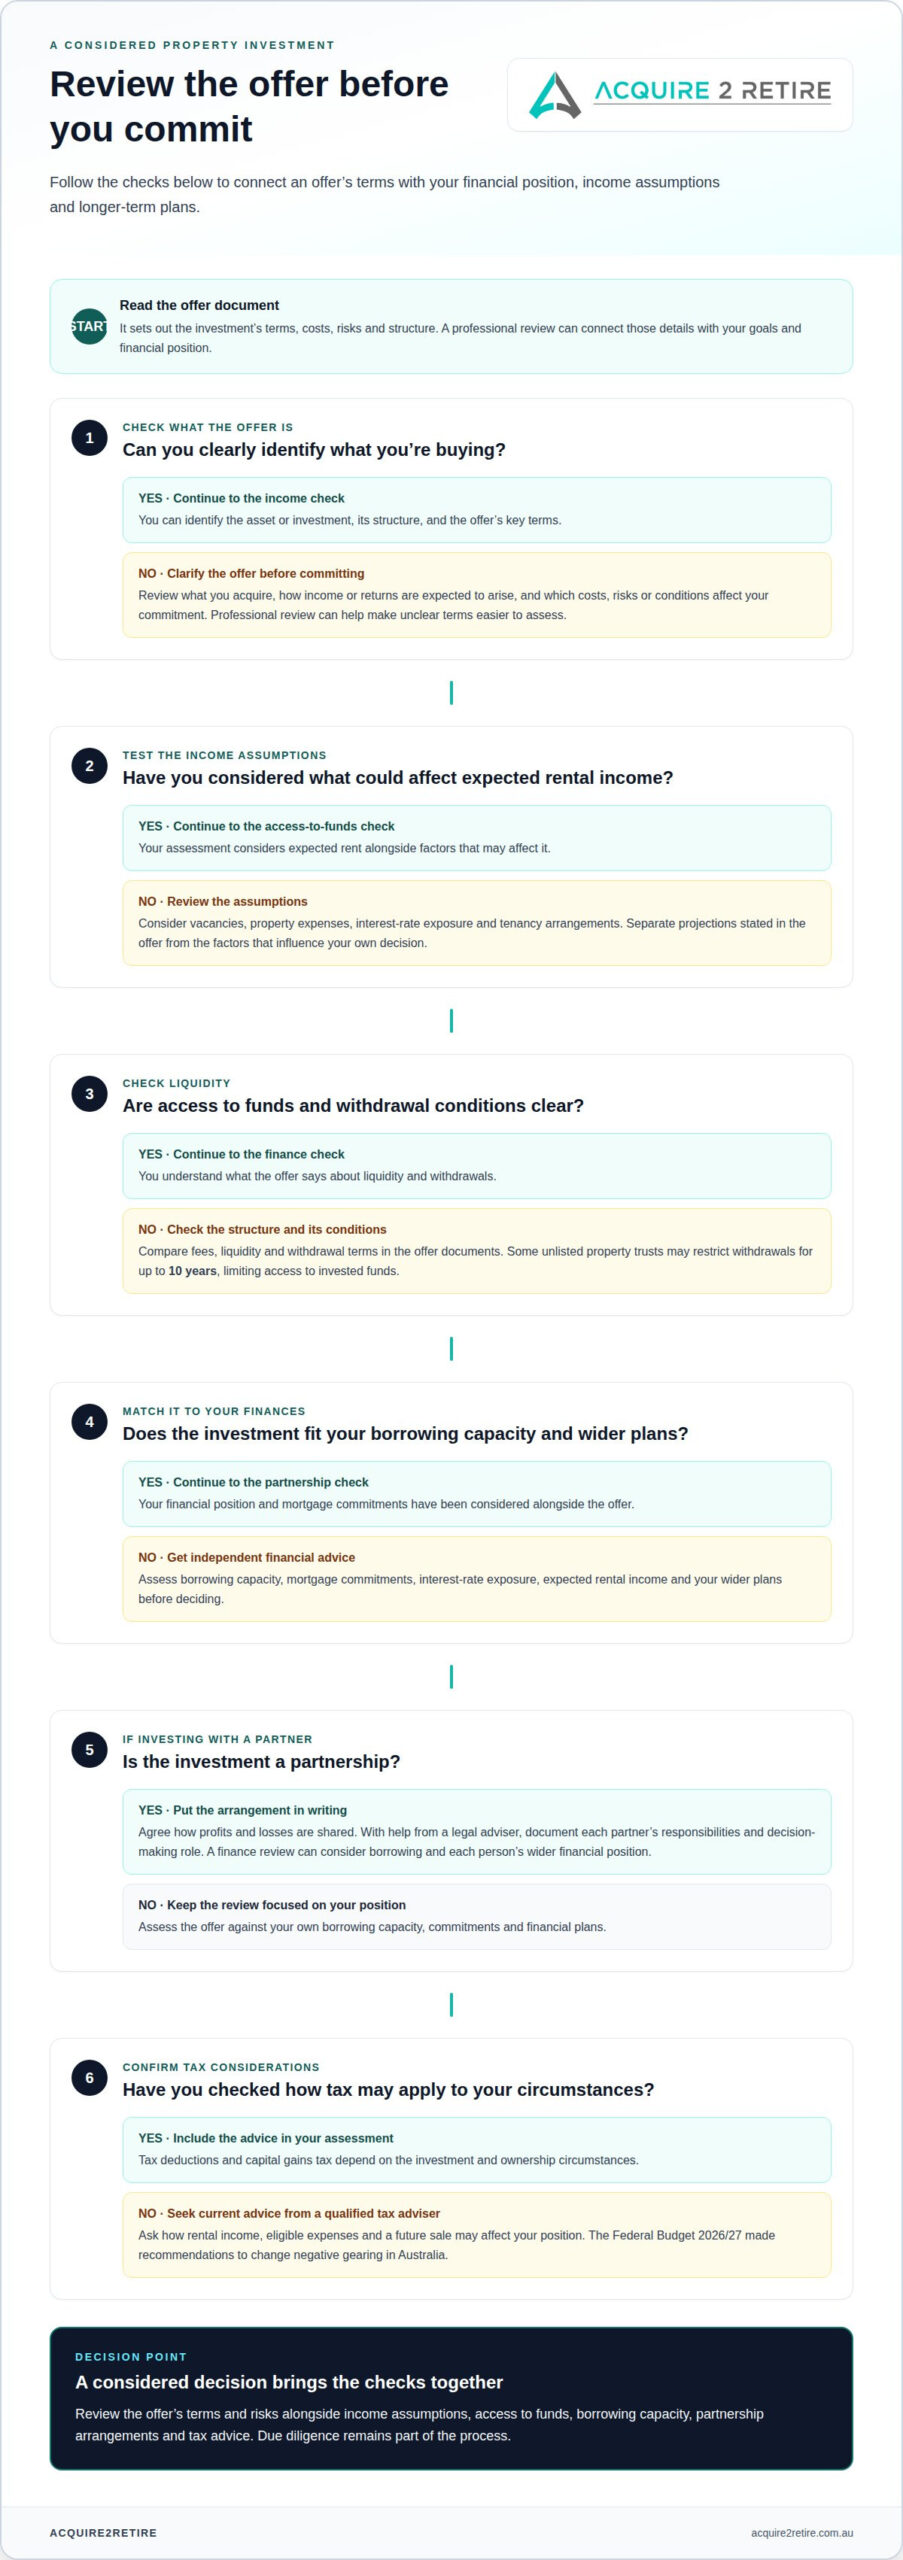
An offer document sets out the terms, costs, risks and structure of a property investment. A professional review connects those details with your goals, financial position and plans for the property market. It can clarify what you’re buying, how income is expected to arise, and which conditions affect your commitment. This matters before signing or making an application to borrow, when unclear terms can shape your obligations.
Independent financial advice can assess whether a proposed investment fits your borrowing capacity, mortgage commitments and wider plans. The review can consider interest-rate exposure, expected rental income and the effect of vacancies or property expenses. If tenants are part of the investment, tenancy arrangements also matter to the income assumptions. A clear assessment helps separate the offer’s stated projections from the factors that influence your personal decision.
Australian property trusts and crowdfunding structures pool investment into property-related opportunities, but their terms and risks differ. Fees depend on the structure and should be set out in its offer documents, alongside liquidity and withdrawal conditions. Some unlisted property trusts may restrict withdrawals for up to 10 years, which can limit access to invested funds. A professional review can explain how those restrictions affect your plans before you invest.
For a property investment partnership, agree how profits and losses will be shared. Document the arrangement with help from a legal adviser, so each partner’s responsibilities and decision-making role are clear. This is especially relevant when partners contribute different amounts or have different borrowing commitments. A finance review can also consider how the partnership structure affects borrowing and each person’s wider financial position.
The Federal Budget 2026/27 made recommendations to change negative gearing in Australia. Seek current tax advice before making property investment decisions, including how rental income, deductible expenses and a future sale may affect your position. For a clearer view of the finance considerations, explore property investment finance guidance as part of your review.
Long-term financial planning and equity growth
Property investment is a long-term plan: gradual value growth and building equity matter more than instant wealth. A financial strategy links buying decisions with borrowing capacity, rental income and future goals. For example, an investor aiming to grow a portfolio can consider whether to hold one property or use equity later. A personalised wealth plan can account for cash flow as well as potential growth.
Equity is the difference between a property’s value and the debt secured against it. In Australia, most lenders may let borrowers access up to 80% of a property’s value, although limits vary between institutions. That figure is a lending threshold, not a deposit amount automatically available to spend. The lender’s assessment and the existing loan balance affect the equity that can be used.
Consider the example of an Australian property valued at A$500,000, with an existing home loan of A$350,000. Borrowing up to 80% of its value would mean borrowing up to A$400,000 against it. After accounting for the existing loan, the example leaves A$50,000 in accessible equity. This illustrates how a professional finance assessment can connect a property’s value with a possible deposit.
Cash-out refinancing can let an owner borrow against equity and use the additional funds to buy another property outright or contribute a deposit. It is described as an option for owners with about 20% equity in an existing property. The additional borrowing increases debt, so a tailored strategy weighs repayments against household finances, rental income and the intended holding period.
Using home equity can reduce the cash needed upfront, but it also links the existing property to a new borrowing decision. A professional can model how different borrowing amounts affect repayments and available funds, then align the purchase with longer-term investment goals. That keeps equity growth connected to a workable financial plan, rather than treating available borrowing as a reason to buy.
Potential income and capital growth
Rental income and capital growth are separate parts of an investment’s potential return. Rent can contribute to ongoing cash flow, while capital growth comes from an increase in property value over time. Assess both alongside costs, financing and your circumstances, rather than treating a strong rental return as proof of overall performance.
Rental yields, vacancy rates and capital growth vary across Australian locations. Compare local rental income with purchase prices, vacancy trends and historical property values; low vacancy rates can indicate stronger rental demand. This comparison can show whether a location suits an income-focused strategy, a growth objective or a balance of both.
Location deserves close attention: one market estimate attributes 60% to 80% of an investor’s return to the area. That makes local employment, transport, amenities and tenant demand relevant to an estate decision. A property in a well-connected neighbourhood, for example, may appeal to a different tenant pool than a similar property with fewer nearby services.
Rental figures need context. A shortfall between rent and costs shows why rent alone doesn’t reveal an investment’s position: loan repayments and property expenses also affect cash flow. Reviewing the full income-and-cost picture helps clarify how much an investor needs to support the property.
Historical property value trends can inform a capital growth assessment, but past movement isn’t a substitute for considering current local conditions. Smaller properties can cost less to maintain and may still have potential to increase in value. Compare each property’s rental prospects, condition and location in light of the role it is meant to play in your portfolio.
To assess a potential purchase, bring rental assumptions, vacancy information, property expenses and growth factors into one view. A structured investment strategy discussion can help connect those factors with your income goals and portfolio plans.
Acquire2Retire
Acquire2Retire helps Australian investors bring property choices, finance and long-term wealth goals into a considered plan. Its Planning & Strategy, Acquisition, Finance and Tenancy offerings can support the connected decisions involved in building a property portfolio, from setting investment priorities to coordinating tenancy arrangements.
Turn to Acquire2Retire when market information feels scattered, or when you want professional guidance to assess an investment against your financial position and plans. A focused discussion can help clarify which questions matter most before you decide on a property or next step.
Contact Acquire2Retire to discuss your property investment plans.
Take the next step with a clear investment plan
A considered property decision starts with knowing what you want your investment to do for you. Before moving towards a purchase, define the priorities that matter most, such as income, potential growth, borrowing comfort and how the investment fits your wider financial plans. That gives professional advice a useful point of focus and helps keep further research relevant to your circumstances.
Finding how to invest in property without researching for months doesn’t mean rushing past important decisions. It means having a structured process that connects your goals with suitable options and the next practical steps. Acquire2Retire can support that process through Planning & Strategy, Acquisition and Finance, helping bring investment objectives and property decisions into alignment.
If you’re ready to explore a considered approach to property investing, contact Acquire2Retire to discuss your options. A clear starting point can make the path ahead feel more manageable, while leaving room to make decisions at a pace that suits you.
Frequently Asked Questions
What are the fastest ways to invest in Australian property with professional guidance?
A focused investment plan and professional acquisition support can narrow the search to properties that fit your goals and finances. The adviser can align market research, property selection and finance considerations, helping you prioritise relevant options rather than assess every listing. Speed should come from a clear scope and coordinated decisions, not skipping due diligence or committing before you understand the offer.
What deposit and upfront costs are needed to buy an Australian investment property?
There’s no single deposit that applies to every Australian investment purchase; the amount depends on the property, lender and borrowing structure. Stamp duty is typically 4-5% of the purchase price, and Lenders Mortgage Insurance applies to loans with a loan-to-value ratio above 80%. Include these costs when assessing the funds needed to complete a purchase.
What property checks and due diligence can a property investment professional arrange before investing in Australia?
A property investment professional can conduct market research and due diligence, identify suitable assets and assess factors such as location, condition, sales history, comparable sales and rental demand. For example, comparing a property’s price with similar sales can help put its value in context. Review offer documents carefully, and direct legal and tax questions to appropriately qualified advisers.